Use this free Mortgage Group Calculator NL to estimate your monthly mortgage payment, total interest cost, and overall mortgage cost in Newfoundland and Labrador, Canada. Enter your home price, down payment, interest rate, and amortization period to get a quick estimate for your mortgage planning.
Mortgage Group Calculator NL
Estimate your mortgage payment and total borrowing cost in Newfoundland & Labrador.
Mortgage Estimate
This calculator provides an estimate based on the information entered. Actual mortgage payments can vary depending on lender terms, payment frequency, mortgage insurance, fees, taxes, and other costs.
What Is a Mortgage Group Calculator NL?
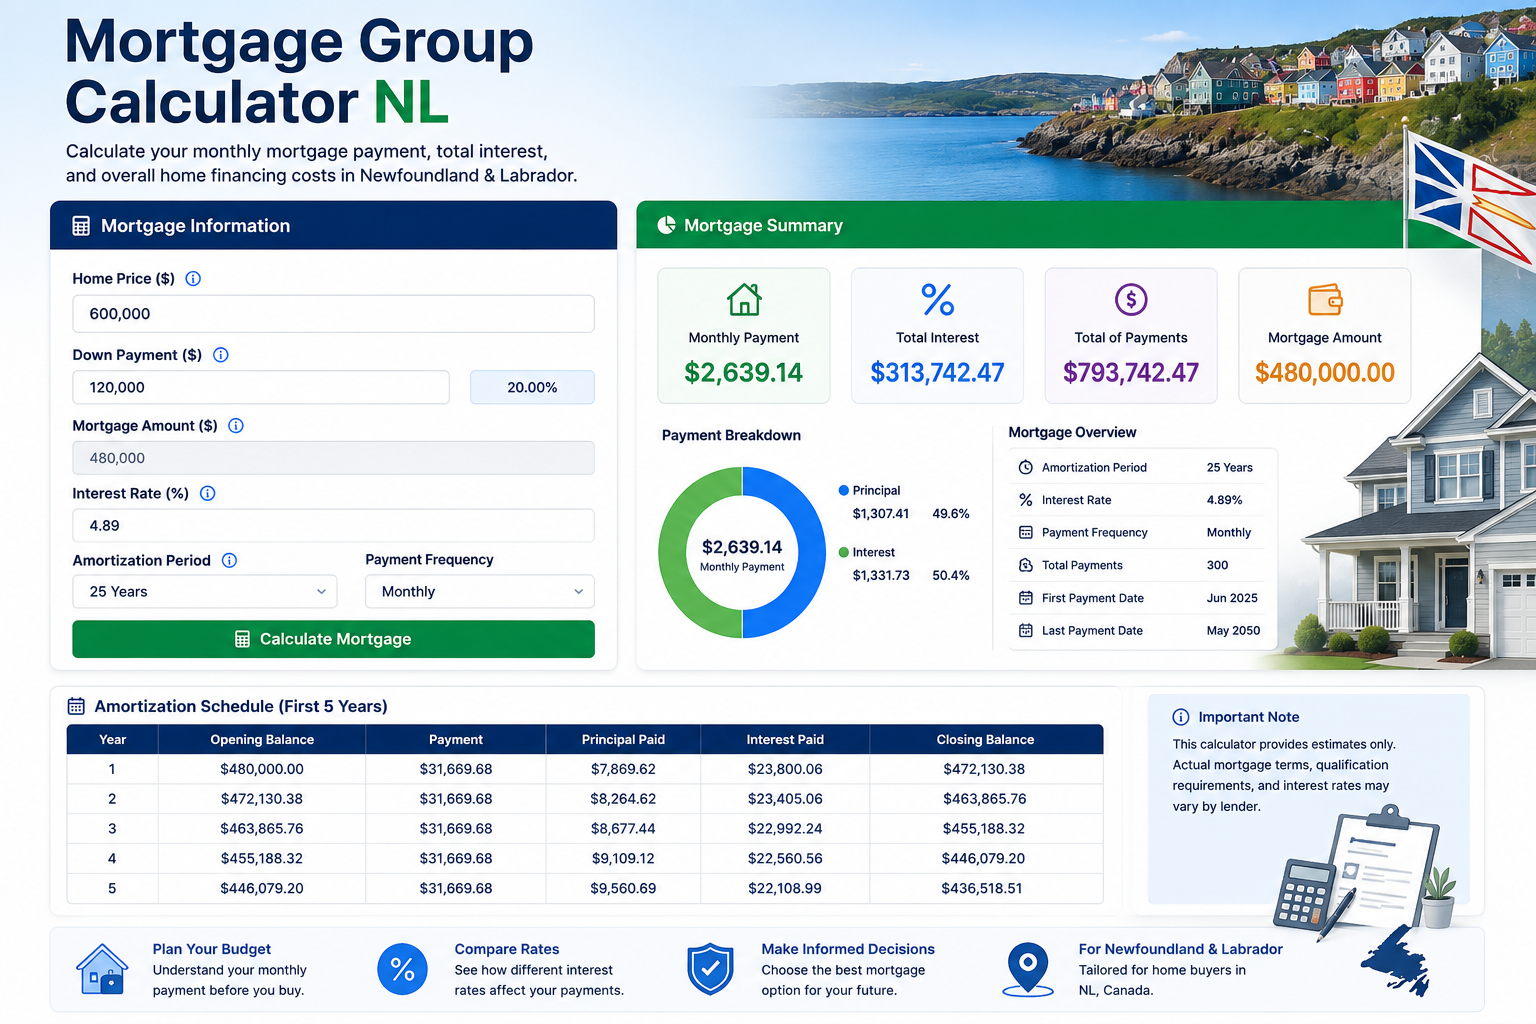
A Mortgage Group Calculator NL is a mortgage planning tool designed for people who want to estimate the cost of borrowing money to purchase a home in Newfoundland and Labrador. By entering the home price, down payment, interest rate, and amortization period, you can estimate the mortgage amount, monthly payment, total interest, and total mortgage cost.
Mortgage calculations can be difficult to work out manually because interest is applied over many monthly payments. A calculator makes it easier to test different scenarios and understand how changes to the down payment, interest rate, or amortization period can affect the cost of a mortgage.
The calculator on this page is intended for general planning and comparison. It does not replace an official mortgage quote from a bank, credit union, broker, or other mortgage provider.
How Does the Mortgage Group Calculator NL Work?
The calculator starts with the purchase price of the property and subtracts the down payment to determine the estimated mortgage principal. It then uses the interest rate and amortization period to calculate an estimated monthly payment.
The calculation assumes monthly mortgage payments and a standard fixed-rate amortization formula. Your actual mortgage may use different payment frequencies, compounding conventions, fees, insurance requirements, or other lender-specific terms.
1. Home Price
Enter the purchase price of the home or property. For example, if the property costs $400,000, enter 400000 in the Home Price field.
2. Down Payment
Enter the amount you plan to pay upfront. The down payment reduces the amount that needs to be borrowed through the mortgage.
3. Interest Rate
Enter the annual mortgage interest rate as a percentage. For example, an interest rate of 5.25% should be entered as 5.25.
4. Amortization Period
Enter the number of years over which you expect to repay the mortgage. A longer amortization can reduce the required monthly payment, but it can also result in more interest being paid over the life of the mortgage.
What Does the Mortgage Calculator Show?
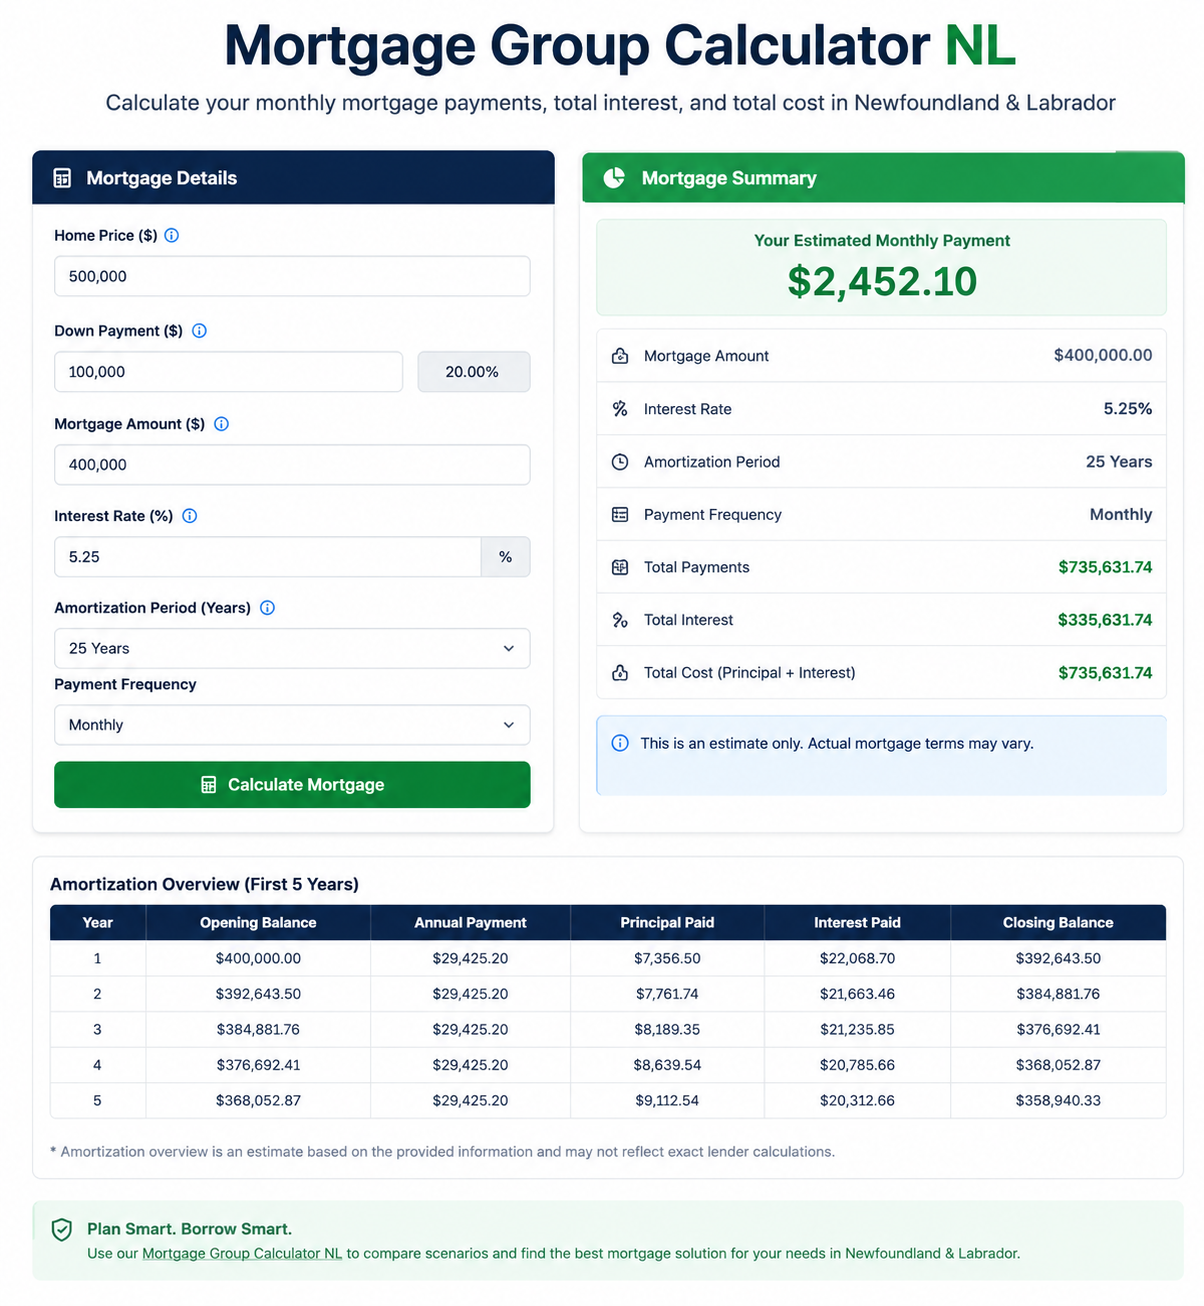
After you click the Calculate Mortgage button, the calculator provides four main results.
- Mortgage Amount: The estimated amount borrowed after the down payment.
- Estimated Monthly Payment: The estimated principal-and-interest payment based on the entered rate and amortization.
- Total Interest Paid: The estimated interest paid over the full amortization period.
- Total Mortgage Cost: The estimated total of mortgage principal and interest over the amortization period.
Why Use a Mortgage Calculator Before Buying a Home?
Buying a home involves more than comparing property prices. Understanding the potential mortgage payment can help you build a realistic housing budget before making an offer or applying for financing.
A mortgage calculator can also help you compare different scenarios. For example, you can calculate the payment using a smaller down payment and then repeat the calculation using a larger down payment. You can also compare different interest rates or amortization periods.
Benefits of Mortgage Planning
- Estimate monthly mortgage payments.
- Understand the effect of your down payment.
- Compare different interest-rate scenarios.
- Estimate long-term interest costs.
- Create a more realistic housing budget.
- Prepare for conversations with mortgage lenders.
- Compare shorter and longer amortization periods.
- Plan for future homeownership expenses.
Mortgage Principal vs. Interest
The mortgage principal is the amount borrowed to finance the property. Interest is the cost charged by the lender for providing that borrowed money.
With a typical amortizing mortgage, each payment contributes toward both principal and interest. Over time, the outstanding principal generally decreases, which changes how much of each payment goes toward interest and principal.
How Down Payment Affects Your Mortgage
A down payment is the portion of the home's purchase price that you pay upfront rather than borrowing. A larger down payment generally means a smaller mortgage principal.
For example, if a home costs $400,000 and the down payment is $80,000, the basic mortgage amount before considering other costs is $320,000. Increasing the down payment would reduce the amount borrowed.
Buyers should also consider that mortgage insurance requirements can depend on the size of the down payment and other factors. The calculator above does not add mortgage insurance premiums or lender-specific fees to the displayed mortgage amount.
Understanding Amortization Period
The amortization period is the estimated amount of time required to repay the mortgage completely if the mortgage remains on the same repayment schedule. It is different from the mortgage term.
A shorter amortization period usually means higher scheduled payments but can reduce the total interest paid over the repayment period. A longer amortization period generally spreads repayment over more months, which can lower the scheduled payment while increasing the total interest cost.
Mortgage Term vs. Amortization Period
These two mortgage terms are often confused. The amortization period describes the overall repayment schedule, while the mortgage term describes the period for which the current mortgage contract and its conditions apply before renewal or another arrangement.
For this reason, the amortization period entered into this calculator should not be confused with the mortgage term selected from a lender.
Mortgage Planning in Newfoundland and Labrador
Homebuyers in Newfoundland and Labrador can use mortgage calculations as one part of their overall property budget. The mortgage payment is only one housing expense. Depending on the property and location, buyers may also need to budget for property taxes, home insurance, utilities, maintenance, repairs, closing costs, and other expenses.
Before purchasing a property, it can be useful to calculate several mortgage scenarios rather than relying on a single estimate. This gives you a better understanding of how changes in the purchase price, down payment, interest rate, and amortization period can affect your planned payment.
Mortgage Costs You Should Consider
The monthly mortgage payment is important, but it is not the complete cost of owning a home. A realistic homeownership budget should consider several additional expenses.
- Mortgage principal and interest
- Property taxes
- Home insurance
- Utilities
- Routine maintenance
- Unexpected repairs
- Closing and legal costs
- Potential mortgage insurance costs
Mortgage Planning Tips for Homebuyers
Compare Different Down Payments
Use different down payment amounts in the calculator to see how borrowing needs and estimated payments change.
Test Different Interest Rates
Mortgage rates can have a significant effect on borrowing costs. Running multiple scenarios can help you understand how sensitive your payment is to the interest rate.
Consider the Full Housing Budget
Do not base affordability only on the mortgage payment. Include other recurring and unexpected costs associated with owning a home.
Consider the Amortization Carefully
A longer amortization may reduce the scheduled monthly payment, but extending repayment can increase the total amount of interest paid.
Compare Mortgage Offers
Different lenders can offer different rates, terms, fees, and mortgage features. Review the complete terms rather than comparing only the advertised interest rate.
Who Can Use This Mortgage Group Calculator NL?
- First-time homebuyers
- Existing homeowners
- People planning a property purchase
- Homeowners reviewing refinancing scenarios
- Real estate investors
- People comparing mortgage rates
- Anyone building a home-buying budget
Common Mortgage Calculation Mistakes
- Looking only at the purchase price.
- Ignoring interest costs over the repayment period.
- Forgetting property taxes and insurance.
- Not budgeting for maintenance and repairs.
- Assuming the calculator result is an official lender quote.
- Confusing mortgage term with amortization period.
- Not comparing multiple mortgage scenarios.
Frequently Asked Questions About Mortgage Group Calculator NL
1. What is a Mortgage Group Calculator NL?
A Mortgage Group Calculator NL is an online tool that estimates mortgage payments and borrowing costs using a home's purchase price, down payment, interest rate, and amortization period.
2. Is this Mortgage Group Calculator NL free?
Yes. The calculator on this page is free to use and can be used to compare different mortgage scenarios.
3. How is the monthly mortgage payment calculated?
The calculator uses the mortgage amount, monthly interest rate, and total number of monthly payments to estimate the monthly principal-and-interest payment.
4. Does this calculator include property taxes?
No. Property taxes are not included in the displayed mortgage payment. They should be considered separately when creating a complete homeownership budget.
5. Does the calculator include mortgage insurance?
No. The calculator provides a basic mortgage principal-and-interest estimate and does not automatically add mortgage insurance premiums or lender-specific fees.
6. What happens if I increase my down payment?
Increasing the down payment reduces the amount that needs to be borrowed. This can reduce the calculated monthly payment and the interest cost associated with the smaller mortgage principal.
7. Does a longer amortization reduce the monthly payment?
Generally, spreading the same mortgage over a longer repayment period reduces the scheduled monthly payment, but it can increase the total interest paid over the full amortization period.
8. What is the difference between mortgage term and amortization?
The amortization period refers to the overall repayment schedule, while the mortgage term refers to the period covered by the current mortgage contract before renewal or another arrangement.
9. Can I use this calculator for Newfoundland and Labrador homes?
Yes. The calculator is designed as a general mortgage planning tool for users researching home financing in Newfoundland and Labrador. It uses Canadian dollars for the displayed results.
10. Is the result an official mortgage quote?
No. The result is an estimate for planning and comparison. Actual mortgage payments and borrowing costs depend on the lender, mortgage product, rate, payment frequency, insurance, fees, and other applicable terms.
Final Thoughts
The Mortgage Group Calculator NL can help Newfoundland and Labrador homebuyers understand how the purchase price, down payment, interest rate, and amortization period affect mortgage costs. By testing different scenarios, you can estimate your monthly payment and compare the potential long-term interest cost before making important financing decisions.
Remember that a mortgage payment is only one part of the total cost of owning a home. Property taxes, insurance, utilities, maintenance, closing costs, mortgage insurance, and other expenses should also be considered when preparing your home-buying budget. Use the calculator as a starting point, then confirm the actual terms and costs with a qualified Canadian mortgage professional or lender.